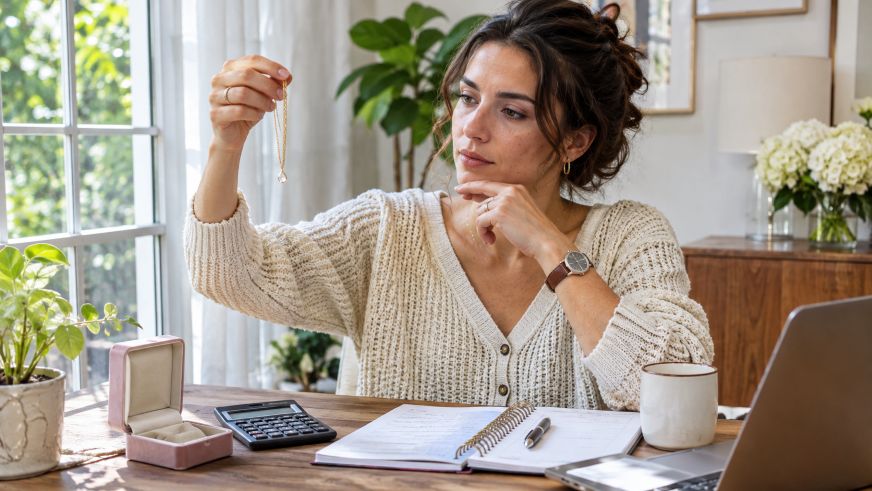
Jewelry purchases are discretionary expenses that compete with essential financial responsibilities. Housing, groceries, transportation, debt payments, and savings usually take priority in a household budget. However, buying a necklace, bracelet, or ring does not necessarily create financial problems. The challenge is finding room for personal purchases without reducing money needed for everyday living and future plans.
Careful planning allows consumers to enjoy jewelry while maintaining control over their spending. Comparing materials, checking prices, and setting a savings target can make purchases more manageable. For example, jewelry from Aqua Gold provides a reference point for examining sterling silver, gold-plated designs, and moissanite accessories. Understanding these material differences helps shoppers compare prices and consider long-term ownership costs before making financial commitments.
Why Jewelry Purchases Need a Separate Budget
Personal purchases can become difficult to manage when they are mixed with essential expenses. A small purchase might appear affordable, but several unplanned expenses can reduce the money available for savings or emergencies.
The Consumer Financial Protection Bureau (CFPB) recommends reviewing spending patterns and including savings contributions and occasional expenses in a monthly budget. This approach helps consumers understand their available income before committing to optional purchases.
Jewelry should generally come from money remaining after essential expenses, required debt payments, and planned savings. Creating a separate spending category also makes it easier to recognize when a purchase exceeds available funds.
7 Steps to Budget for Jewelry Purchases
1. Review Your Current Financial Situation
Start by calculating your monthly take-home income. Next, subtract essential expenses, debt obligations, and regular savings contributions. Include less frequent costs such as insurance, medical appointments, and household repairs.
The remaining amount represents money potentially available for discretionary spending. However, it should cover other personal activities too, including entertainment, dining, and hobbies.
If little remains after these deductions, postponing jewelry purchases may be the more practical decision.
2. Establish a Realistic Spending Limit
Decide how much you can comfortably spend before browsing jewelry collections. Your limit should reflect available income rather than the price of a particular item.
For example, someone who can set aside $25 monthly could accumulate $150 over six months. This approach creates a clear purchasing target without disrupting regular expenses.
Consider these budgeting practices:
- Set a maximum amount for each planned purchase.
- Save gradually instead of spending money reserved for necessities.
- Keep jewelry savings separate from emergency funds.
- Review your spending limit when income or expenses change.
These simple boundaries help prevent impulse purchases and encourage deliberate financial decisions.
3. Compare Jewelry Materials Before Buying
Jewelry prices vary depending on metal content, gemstones, craftsmanship, and design. Understanding what each product contains makes comparisons more meaningful.
The Federal Trade Commission (FTC) explains that sterling silver contains 92.5% pure silver. Gold-plated jewelry, meanwhile, has a gold coating applied over another metal. That coating can gradually wear away, depending on its thickness and how the item is used.
Consumers comparing sterling silver, gold-plated metals, and alternative gemstones such as moissanite should consider more than appearance. Metal composition, gemstone characteristics, and expected wear all influence suitability.
A lower initial price may fit a limited budget, but the least expensive option is not automatically the most economical over time.
4. Identify Additional Purchase Costs
The displayed price does not always represent the final amount paid. Delivery charges, taxes, resizing, and optional packaging may increase the total.
Before purchasing, check the following:
- Shipping fees and applicable taxes.
- Ring resizing or necklace adjustments.
- Return shipping and exchange conditions.
- Optional warranties or protection plans.
- Possible currency conversion charges.
These expenses should fit within the original spending limit. Checking store policies also reduces the possibility of unexpected costs after ordering.
5. Consider Long-Term Maintenance Expenses
Jewelry requires appropriate care to preserve its appearance and condition. Some pieces need occasional cleaning, repairs, or professional inspection.
The Gemological Institute of America (GIA) explains that certain gemstones can be affected by heat, chemicals, and improper cleaning methods. Treatments used to improve gemstone appearance may also influence durability and care requirements.
Consumers should ask about cleaning instructions, storage recommendations, and possible repair costs. These details are especially useful when choosing jewelry intended for frequent wear.
Budgeting for maintenance helps shoppers understand the potential lifetime cost rather than focusing exclusively on the purchase price.
6. Avoid Unnecessary Debt for Nonessential Purchases
Credit cards and installment arrangements can make expensive jewelry appear immediately affordable. However, borrowing introduces additional financial obligations.
Interest charges and late fees can increase the final amount paid when balances are not settled as agreed. Monthly installments may also compete with savings goals or necessary household expenses.
For nonessential purchases, saving before buying is often a simpler approach. Consumers using credit should understand the repayment terms and ensure payments fit comfortably within their budgets.
Jewelry should not become a reason to carry expensive debt or postpone important financial commitments.
7. Evaluate Value Beyond the Purchase Price
Price alone does not determine whether jewelry represents a sensible purchase. Frequency of use, personal preference, durability, and maintenance requirements also matter.
A versatile necklace worn regularly may offer greater practical value to its owner than a more expensive accessory rarely used. Similarly, a meaningful gift may justify planned spending without requiring a luxury budget.
Consumers should also avoid assuming that every jewelry purchase is an investment. Resale prices depend on material content, condition, market demand, and other factors. Retail prices do not guarantee future resale value.
How to Keep Jewelry Spending Under Control
Successful budgeting depends on habits that remain practical over time. Maintaining a wish list, comparing alternatives, and allowing time before purchasing can help separate genuine preferences from temporary impulses.
Review your discretionary spending regularly. If financial priorities change, adjust jewelry plans accordingly. A new household expense, reduced income, or upcoming major purchase may justify delaying an accessory purchase. Understanding the principles of long-term financial planning can also help consumers balance personal spending with savings, debt management, and future financial goals.
It is equally important to protect emergency savings. Money reserved for unexpected medical bills, repairs, or income interruptions should remain available for those purposes.
Conclusion
Buying jewelry can fit within a responsible financial plan when spending decisions are deliberate. Setting limits, comparing materials, accounting for additional costs, and avoiding unnecessary debt help consumers balance personal enjoyment with financial responsibilities.
The most useful principle is straightforward: purchase what your budget can support without sacrificing essential expenses or long-term savings. As circumstances change, reviewing priorities will help ensure that occasional jewelry purchases remain manageable rather than becoming a source of financial pressure.